Crude Tanker Rates Stabilise as Post-Spike Correction Slows
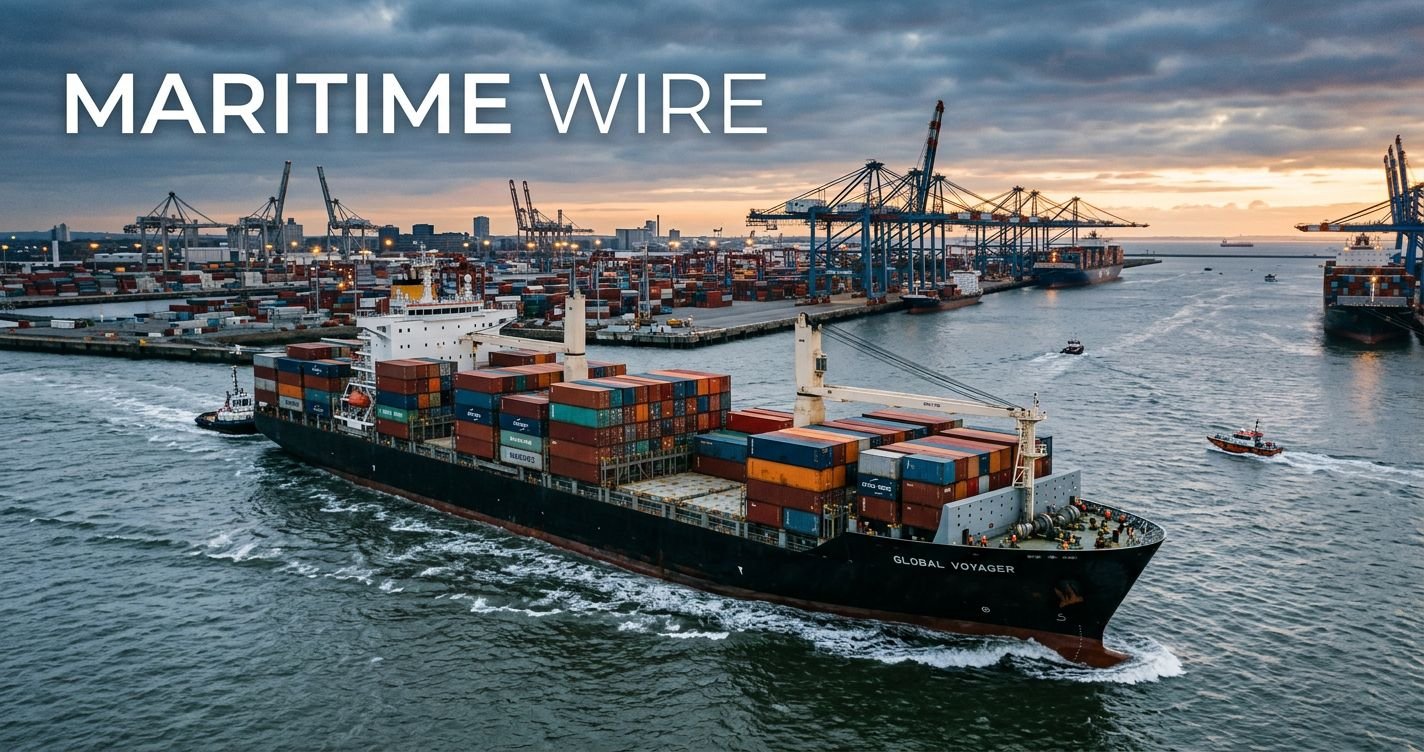
Global crude tanker spot rates appear to be finding a floor following a sharp downward trajectory from October’s record highs.
A recent surge in chartering market activity suggests that charterers are re-entering the market as lower freight costs make crude oil transport economically viable once again.
Market Correction Slows Down
According to market data from the Baltic Exchange, freight rates for Very Large Crude Carriers (VLCCs), Suezmaxes, and Aframaxes experienced a contraction of up to 50% to 63% from their October peaks.
The initial tanker market correction was driven by a combination of recovering Middle Eastern exports through alternative channels, increased vessel availability in East Asia, and Asian refiners pausing purchases due to unsustainably high freight costs.
However, the rapid decline in crude tanker rates has begun to lose momentum. Analysts from Vortexa noted that as laden vessels finish discharging cargoes across Asian ports, the market is finding a balance point. Lower freight rates have successfully reignited interest within the chartering market, encouraging charterers to step back in and cover late-year crude oil transport requirements.
Drivers Behind Market Stabilization
The ongoing tanker market correction reflects a shift in market leverage back toward charterers. During the height of the October rally, extreme geopolitical risk premiums and longer-haul voyages from West Africa, Brazil, and the U.S. Gulf to Asia severely constrained tonnage availability. As Middle Eastern crude supply routes normalized via alternative Red Sea and Gulf of Oman pipelines, demand for long-haul Atlantic crude transport softened.
Despite the substantial drop, current crude tanker rates remain exceptionally strong compared to historical benchmarks. According to shipbroking reports from Fearnleys, daily earnings on key trade routes like Oman to China—while down significantly from October peaks—remain far above break-even levels for vessel operators. Shipowners continue to hold firm on bids for forward laycans, supported by high ongoing geopolitical risks and potential winter trade volatility.
The stabilization of crude tanker rates provides much-needed visibility for fourth-quarter vessel scheduling and budgeting. While the post-spike correction has trimmed record profit margins, the pricing floor established by renewed chartering demand indicates that underlying structural tightness in the global tanker fleet will continue to support firm freight levels through the remainder of the year.